Medicare Advantage PPO vs HMO — Complete Guide 2026
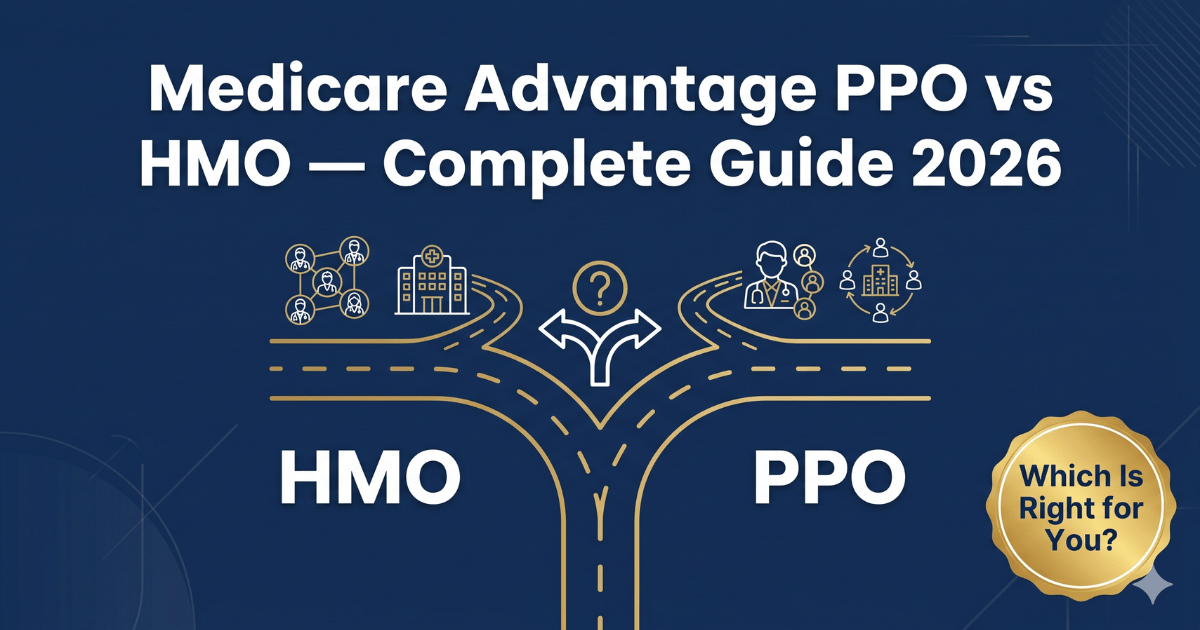
Medicare Advantage PPO vs HMO — which is better in 2026? If you are considering Medicare Advantage one of the most important decisions you will make is choosing between a PPO (Preferred Provider Organization) and an HMO (Health Maintenance Organization) plan. These two Medicare Advantage plan types work very differently — and choosing the wrong one can result in unexpected bills, loss of access to your preferred doctors, and frustrating prior authorization delays. In this complete guide we explain everything about Medicare Advantage PPO vs HMO in 2026 — how each type works, key differences, costs, provider access, and which type is better for different types of Medicare beneficiaries. All information is sourced from Medicare.gov and CMS.gov.
Also Read —
- Medicare Advantage vs Original Medicare 2026
- Medicare Advantage vs Medicare Supplement 2026
- Best Medicare Advantage Plans by State 2026
What You Will Learn — Medicare Advantage PPO vs HMO 2026
- What is a Medicare Advantage HMO plan
- What is a Medicare Advantage PPO plan
- Key differences between Medicare Advantage PPO and HMO
- Cost comparison — PPO vs HMO Medicare Advantage
- Provider access — PPO vs HMO
- Referral requirements — PPO vs HMO
- Who should choose Medicare Advantage HMO
- Who should choose Medicare Advantage PPO
- Frequently asked questions about Medicare Advantage PPO vs HMO 2026
What Is a Medicare Advantage HMO Plan?
A Medicare Advantage HMO — Health Maintenance Organization — is a Medicare Advantage plan that requires you to use a specific network of doctors, hospitals, and healthcare providers for your medical care. HMO plans are the most common type of Medicare Advantage plan in the United States and are the plan type most people encounter when shopping for Medicare Advantage coverage.
How Medicare Advantage HMO Plans Work
With a Medicare Advantage HMO you select a primary care physician (PCP) who serves as the coordinator of your healthcare. Your PCP provides your routine and preventive care and provides referrals when you need to see specialists. Most HMO plans require referrals from your primary care physician before you can see a specialist — without a referral your specialist visit may not be covered or may be subject to higher cost-sharing.
HMO plans restrict coverage to providers within the plan’s contracted network. If you see an out-of-network provider — except in emergency situations — your HMO plan will not pay for the services. This network restriction is the defining characteristic of HMO coverage and the primary limitation compared to PPO plans.
Types of Medicare Advantage HMO Plans
HMO plans — standard HMO requiring referrals for specialist visits
HMO-POS (Point of Service) — an HMO with a limited option to see out-of-network providers at higher cost-sharing. HMO-POS plans provide more flexibility than standard HMOs while maintaining lower premiums than PPOs.
What Is a Medicare Advantage PPO Plan?
A Medicare Advantage PPO — Preferred Provider Organization — is a Medicare Advantage plan that gives you more flexibility to see doctors both inside and outside the plan’s network. PPO plans do not require you to choose a primary care physician and do not require referrals for specialist visits.
How Medicare Advantage PPO Plans Work
With a Medicare Advantage PPO you can see any Medicare-accepting provider — both in-network and out-of-network — without a referral. However you pay less when you use in-network providers. When you use out-of-network providers you pay a higher coinsurance or copay — but the plan still covers a portion of the cost.
PPO plans give you the freedom to:
- See any specialist directly without a referral from a primary care physician
- Use out-of-network providers at higher cost-sharing
- Access care when traveling outside your home service area at any Medicare-accepting provider
- Make your own healthcare decisions without navigating a referral system
Key Differences Between Medicare Advantage PPO and HMO
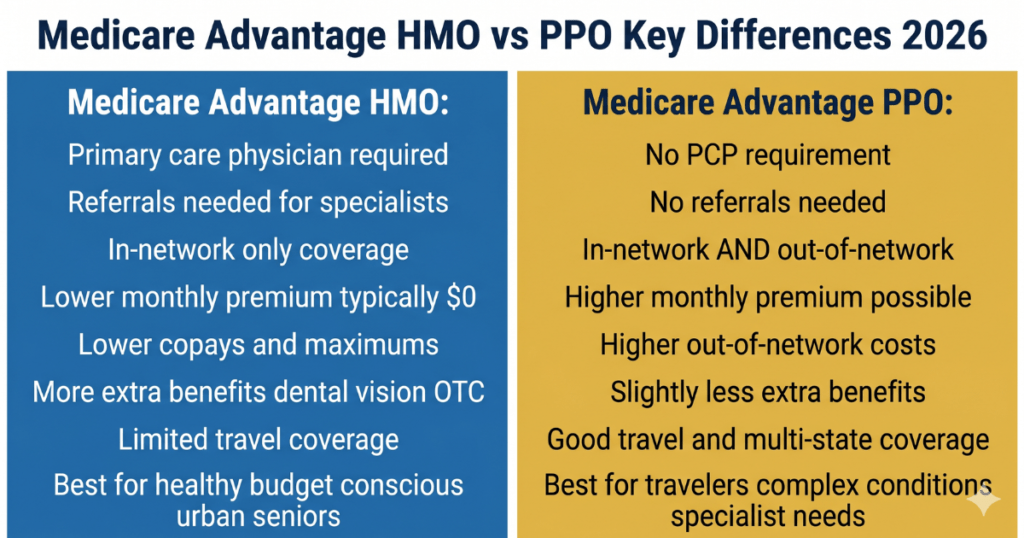
Here is a comprehensive side-by-side comparison of the key differences between Medicare Advantage PPO and HMO plans in 2026:
Primary Care Physician Requirement
HMO — required to choose a primary care physician who coordinates all care
PPO — no primary care physician requirement. You can go directly to any provider.
Referrals for Specialists
HMO — referrals from your primary care physician typically required before seeing a specialist. Without a referral specialist visits may not be covered.
PPO — no referrals required. You can see any specialist directly without prior authorization from a primary care physician.
Network Restrictions
HMO — coverage restricted to in-network providers for non-emergency care. Out-of-network care is not covered except for emergencies.
PPO — in-network and out-of-network coverage available. You pay less for in-network care but can access out-of-network providers at higher cost.
Monthly Premium
HMO — typically lower monthly premiums than comparable PPO plans. Many HMO plans have $0 additional monthly premium beyond the Part B premium.
PPO — typically higher monthly premiums than comparable HMO plans due to the greater provider flexibility. Some PPO plans still offer $0 additional premium but this is less common than with HMOs.
Out-of-Pocket Maximum
HMO — lower annual out-of-pocket maximum for in-network services — typically $3,000 to $5,000 on competitive plans. Some plans as low as $0.
PPO — separate out-of-pocket maximums for in-network (lower) and out-of-network (higher) services. In-network maximum typically $3,000 to $5,000. Out-of-network maximum can be $7,500 to $12,000 or more.
Specialist Access
HMO — specialist access requires referral from PCP. May require prior authorization for certain specialist types.
PPO — direct specialist access without referral. Can see any specialist in-network or out-of-network.
Coverage Area
HMO — coverage limited to plan’s defined service area for non-emergency care. Problems arise when traveling or living in multiple locations.
PPO — in-network coverage in defined service area. Out-of-network coverage available nationwide making PPO better for travelers and snowbirds.
Prior Authorization
HMO — prior authorization frequently required for specialist visits, procedures, and medications. The PCP referral system serves as a form of prior authorization.
PPO — prior authorization still required for major procedures and specialist care but the referral process is eliminated for routine specialist access.
Extra Benefits
HMO — typically more generous extra benefits — dental, vision, hearing, OTC allowances — because lower administrative costs allow more benefit investment.
PPO — typically slightly less generous extra benefits than comparable HMO plans due to higher administrative costs of managing both in-network and out-of-network claims.
Cost Comparison — Medicare Advantage PPO vs HMO 2026
Monthly Premium
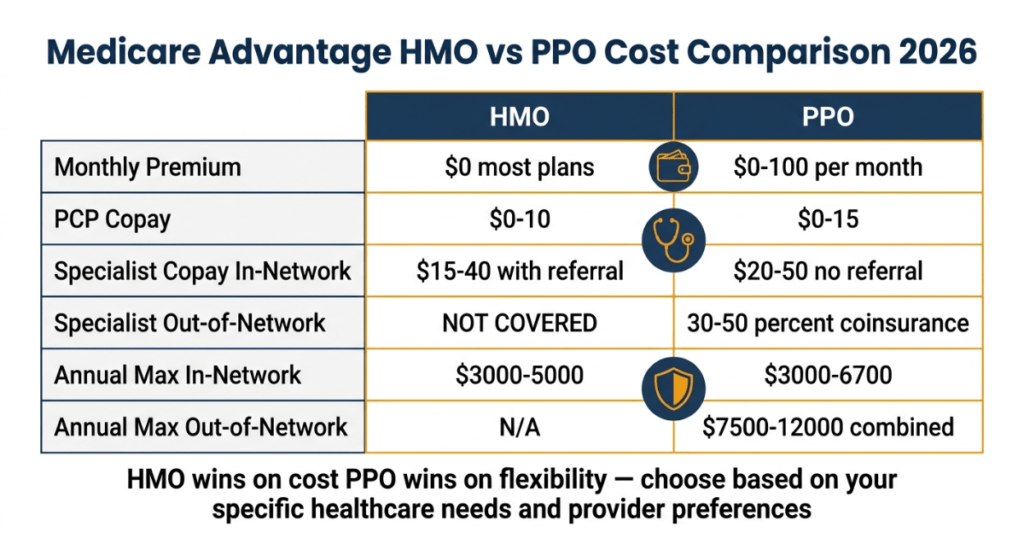
Medicare Advantage HMO plans typically offer $0 additional monthly premium in most competitive markets. You pay only the standard $185.00 Part B premium.
Medicare Advantage PPO plans may charge $0 to $100 additional monthly premium. In some markets PPO plans with $0 additional premium are available but they typically have higher cost-sharing than comparable HMOs.
Copays and Coinsurance
HMO plans typically charge lower copays for in-network services:
- Primary care visit — $0 to $10
- Specialist visit (with referral) — $15 to $40
- Urgent care — $35 to $75
PPO plans typically charge similar copays for in-network services but add out-of-network cost-sharing:
- Primary care in-network — $0 to $15
- Specialist in-network — $20 to $50
- Specialist out-of-network — 30% to 50% coinsurance
- Out-of-network maximum — $7,500 to $12,000
Annual Out-of-Pocket Maximum
HMO in-network maximum — typically $3,000 to $5,000 on many competitive plans — some as low as $0 to $1,500.
PPO in-network maximum — typically $3,000 to $6,700 for in-network services. PPO combined in and out-of-network maximum — typically $7,500 to $12,000.
True Cost Comparison
For a healthy beneficiary using primarily in-network providers the HMO typically has:
- Lower monthly premium
- Lower copays
- Lower annual maximum
For a beneficiary who needs out-of-network providers or specialist access without referrals the PPO provides:
- More provider flexibility at higher cost
- Out-of-network coverage that HMO does not provide
- Direct specialist access without referral delays
Provider Access — PPO vs HMO
Provider access is the most critical difference between Medicare Advantage PPO and HMO plans — and it is the factor that most often determines which plan type is right for a specific Medicare beneficiary.
Medicare Advantage HMO Provider Access
HMO plans restrict your coverage to in-network providers. Before enrolling in an HMO you must verify that all your current providers — primary care physician, all specialists, hospitals, diagnostic centers, and labs — are in the HMO’s network.
When a provider leaves an HMO network your access to that provider under the plan ends — you either pay out-of-pocket or switch providers. Network changes happen annually — doctors can leave or join HMO networks on January 1.
HMO network restrictions create particular challenges for:
- Patients with established relationships with specific specialists
- Patients requiring care at specific hospitals (e.g. academic medical centers or cancer centers)
- Patients who receive care in multiple geographic areas
Medicare Advantage PPO Provider Access
PPO plans allow you to see any Medicare-accepting provider — with lower cost-sharing for in-network providers and higher (but still covered) cost-sharing for out-of-network providers.
This out-of-network coverage is one of the most important PPO advantages for certain Medicare beneficiaries:
- Snowbirds and frequent travelers who need medical care in multiple states
- Patients with complex conditions who may need to see out-of-network specialists
- Patients who want the option to access major academic medical centers even if not in-network
The PPO Out-of-Network Warning
While PPO out-of-network coverage provides valuable flexibility it comes with important cost warnings. Out-of-network cost-sharing under Medicare Advantage PPO can be very high:
- 30% to 50% coinsurance for out-of-network services
- A separate higher out-of-network out-of-pocket maximum
- Potential balance billing — some out-of-network providers may bill the difference between their charges and the plan’s payment
Always check the PPO plan’s out-of-network cost-sharing before accessing out-of-network providers — the flexibility is valuable but the costs can be significant.
Who Should Choose Medicare Advantage HMO?
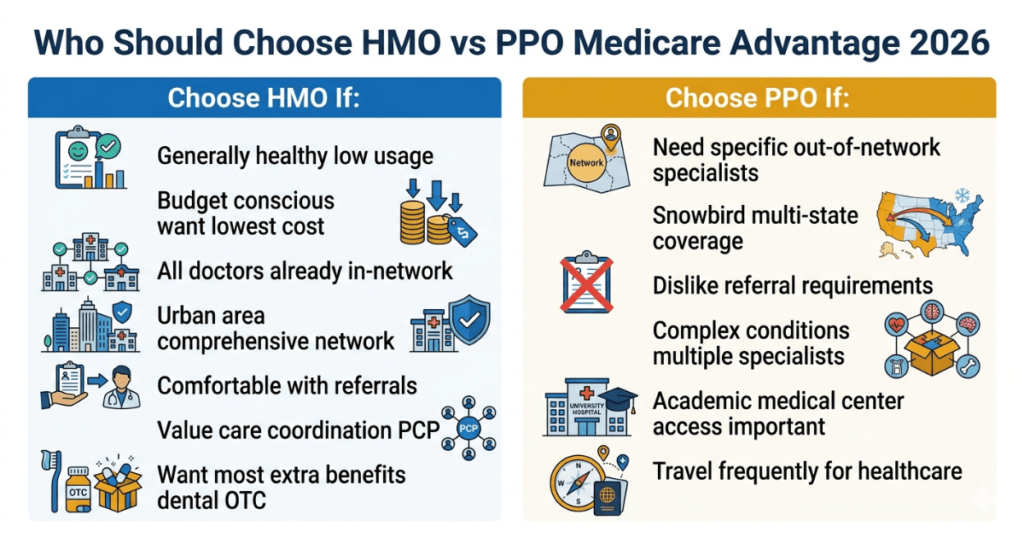
Medicare Advantage HMO is typically the better choice for:
Healthy Seniors with Low Healthcare Usage
Healthy beneficiaries who primarily need preventive care and occasional doctor visits benefit from HMO’s lower premiums, lower copays, and lower out-of-pocket maximums. If all your healthcare needs can be met by in-network providers the HMO’s network restriction is rarely a problem.
Budget-Conscious Seniors
HMO plans typically offer the lowest total cost among Medicare Advantage plan types — lower premiums and lower cost-sharing make HMO the most financially efficient choice for seniors who can accept network restrictions.
Seniors Who Value Coordinated Care
The HMO’s primary care coordination model — with a designated PCP managing all your care — can be advantageous for patients with multiple chronic conditions who benefit from having a single provider coordinating their healthcare.
Urban Seniors with Comprehensive Networks
In major metropolitan areas HMO networks are typically very comprehensive — including most major local providers, hospitals, and specialists. Urban seniors in competitive Medicare markets often find that HMO network restrictions are rarely a practical problem because their preferred providers are already in-network.
Who Should Choose Medicare Advantage PPO?
Medicare Advantage PPO is typically the better choice for:
Seniors Who Need Specific Out-of-Network Providers
If you have established relationships with specific specialists or want access to academic medical centers or specialized hospitals that may not be in the HMO network a PPO provides the flexibility to access these providers at higher but covered cost-sharing.
Snowbirds and Frequent Travelers
Seniors who spend significant time in multiple states — snowbirds — cannot rely on an HMO’s geographically-limited network. PPO out-of-network coverage allows access to healthcare in any location at higher cost-sharing making PPO much more suitable for mobile seniors.
Seniors Who Dislike Referral Requirements
Some seniors find the HMO referral system — requiring PCP approval before seeing specialists — frustrating and potentially delaying necessary care. PPO plans eliminate this requirement allowing direct specialist access.
Seniors with Complex Medical Conditions
Patients with complex conditions requiring multiple specialists may benefit from PPO’s direct specialist access and out-of-network flexibility — particularly if they need to see specialists at major academic or specialty centers.
Frequently Asked Questions — Medicare Advantage PPO vs HMO
What is the difference between Medicare Advantage PPO and HMO?
Medicare Advantage HMO requires you to use in-network providers, choose a primary care physician, and get referrals for specialists — but offers lower premiums and copays. Medicare Advantage PPO allows you to see any Medicare-accepting provider without referrals — including out-of-network at higher cost — but typically has higher premiums than HMO plans.
Which is better — Medicare Advantage PPO or HMO?
Neither is universally better — the right choice depends on your situation. HMO is better for healthy budget-conscious seniors who can accept network restrictions and prefer lower costs. PPO is better for seniors who need specific out-of-network providers, travel frequently, dislike referral requirements, or have complex conditions requiring multiple specialists.
Do Medicare Advantage HMO plans cover out-of-network providers?
Standard HMO plans cover out-of-network providers only in emergencies — non-emergency out-of-network care is not covered. HMO-POS plans allow some out-of-network access at higher cost-sharing. PPO plans cover both in-network and out-of-network providers.
Are Medicare Advantage PPO plans more expensive than HMO?
Generally yes — PPO plans typically have higher premiums and may have higher cost-sharing for out-of-network services compared to HMO plans. However the additional cost reflects the greater provider flexibility PPO provides.
Do Medicare Advantage HMO plans require referrals?
Standard HMO plans require referrals from your primary care physician before seeing specialists. HMO-POS plans may also require referrals. PPO plans do not require referrals — you can see specialists directly without PCP approval.
Can I switch from Medicare Advantage HMO to PPO?
Yes — you can switch from HMO to PPO during the Annual Election Period from October 15 to December 7. Changes take effect January 1. You can also switch during the Medicare Advantage Open Enrollment Period from January 1 to March 31 with changes effective the first of the following month.
Summary — Medicare Advantage PPO vs HMO 2026
Medicare Advantage PPO vs HMO — the right choice in 2026 depends entirely on your healthcare needs, provider preferences, and budget. HMO plans offer lower costs and often more generous extra benefits with the trade-off of network restrictions and referral requirements. PPO plans offer greater provider flexibility and out-of-network coverage with the trade-off of higher premiums and cost-sharing.
For most healthy budget-conscious seniors in competitive urban Medicare markets HMO provides excellent coverage at the lowest cost. For seniors who travel frequently, need specific out-of-network providers, or prefer direct specialist access without referrals PPO provides valuable flexibility worth the additional cost.
For free personalized help choosing between Medicare Advantage PPO and HMO contact your State Health Insurance Assistance Program (SHIP) at shiphelp.org or call Medicare free at 1-800-633-4227.
This guide is for informational purposes only and is not medical or financial advice. Always verify current plan details at Medicare.gov before making enrollment decisions.
Sources: Medicare.gov | CMS.gov | SSA.gov | AARP.org
Last updated: April 2026 | Author: James Carter, Independent Medicare Research Analyst