Medicare and Travel Coverage — Complete Guide 2026
Medicare and travel coverage in 2026 is one of the most important and most misunderstood aspects of Medicare planning — particularly for the millions of Medicare beneficiaries who travel regularly between states, spend winters in warmer climates as snowbirds, or travel internationally. Understanding exactly how Medicare and travel coverage works in 2026 — what is covered domestically, what is covered internationally, and how different Medicare plans handle travel — can prevent catastrophic surprise medical bills for traveling Medicare beneficiaries. In this complete guide we explain everything about Medicare and travel coverage in 2026. All information is sourced from Medicare.gov and CMS.gov.
Also Read —
- Medicare Advantage vs Original Medicare 2026
- Best Medicare Supplement Plans 2026
- Medigap Plan G vs Plan N 2026
What You Will Learn — Medicare and Travel Coverage 2026
- How Original Medicare covers travel within the United States
- How Medicare Advantage handles travel and out-of-area care
- How Medigap supplements cover travel within the US
- Does Medicare cover international travel
- Medicare travel coverage for snowbirds
- Medicare travel emergency coverage outside the US
- How to prepare your Medicare coverage for travel
- Travel insurance for Medicare beneficiaries
- Frequently asked questions about Medicare and travel coverage 2026
How Original Medicare Covers Travel Within the United States
Medicare and travel coverage within the United States under Original Medicare is one of the most valuable and most underappreciated features of the program.
Original Medicare Covers Any Medicare-Accepting Provider Nationwide
Original Medicare — Parts A and B — covers medically necessary services at any Medicare-participating provider anywhere in the United States — regardless of where you live or where you receive care. This nationwide coverage is one of Original Medicare’s most significant advantages.
What this means for traveling Medicare beneficiaries:
- Emergency care in any state — covered
- Planned specialist visits while traveling — covered
- Hospitalization in any state — covered
- Surgery while traveling — covered
- Physician office visits while away from home — covered
There are no network restrictions under Original Medicare — no in-state requirements, no prior authorization for emergency care across state lines, no limitations on which Medicare-accepting provider you see. A Medicare beneficiary from Minnesota receiving care in Florida, Arizona, or any other state uses their Medicare card exactly the same way they would at home.
Snowbird Coverage Under Original Medicare
For Medicare beneficiaries who spend several months each year in a different state — the classic snowbird pattern of spending winters in Florida, Arizona, Texas, or Hawaii — Original Medicare provides seamless coverage in both home and winter states.
Snowbirds with Original Medicare can:
- See a primary care physician in their winter home at standard Medicare rates
- Access specialists in their winter state without referrals
- Fill prescriptions through Part D — though Part D networks may vary by state
- Receive emergency and non-emergency hospital care in either state
Medicare Part D and Travel
Medicare Part D prescription drug plans have networks that may vary by geography — your preferred pharmacy may be out-of-network in your travel destination. However:
- National pharmacy chains — CVS, Walgreens, Rite Aid, Walmart — are typically in-network nationwide on most Part D plans
- Out-of-network pharmacies can dispense Medicare Part D prescriptions in certain circumstances — ask your Part D plan about out-of-network access
- Mail-order pharmacy through your Part D plan works regardless of your physical location
How Medicare Advantage Handles Travel and Out-of-Area Care
Medicare and travel coverage under Medicare Advantage is significantly more complex and more restrictive than Original Medicare — and this is one of the most important distinctions between the two approaches.
Medicare Advantage Network Restrictions
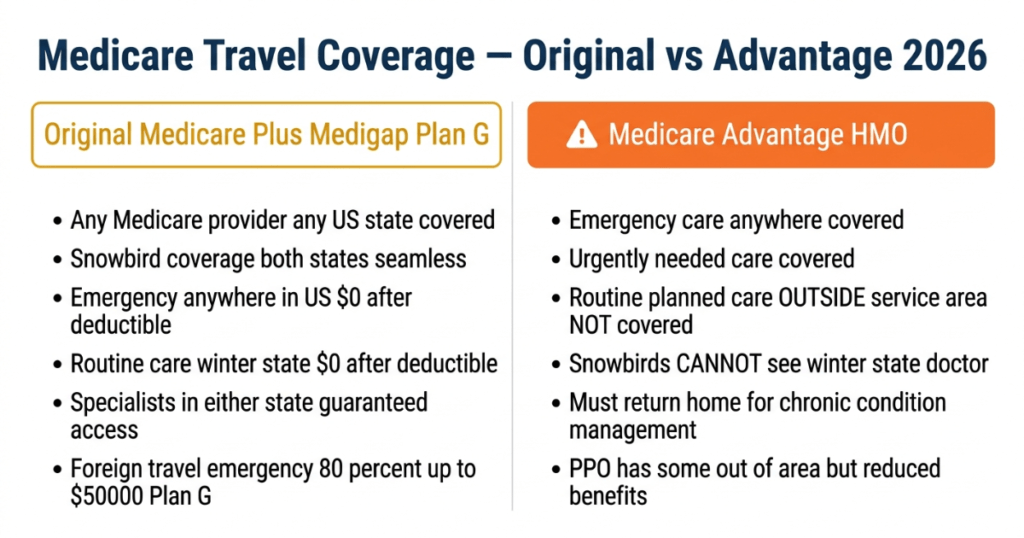
Medicare Advantage plans have defined service areas — geographic regions where the plan’s network of providers operates. When you travel outside your plan’s service area Medicare Advantage coverage becomes restricted:
Emergency Care — Always Covered
All Medicare Advantage plans must cover emergency care anywhere in the United States — regardless of network. If you have a heart attack, stroke, severe injury, or other emergency while traveling your Medicare Advantage plan must cover emergency room care at any US hospital at in-network cost-sharing rates.
Urgently Needed Care — Generally Covered
Medicare Advantage plans must also cover urgently needed care outside the service area — care for a condition that is not an emergency but needs attention before you can reasonably return home. Examples include a serious infection, broken bone, or severe respiratory illness while traveling.
Planned Non-Emergency Care — Problematic
Here is where Medicare Advantage travel coverage becomes significantly limited:
HMO Medicare Advantage plans — virtually never cover planned non-emergency care outside the service area. A Medicare Advantage HMO member spending 5 months in Florida cannot see a Florida primary care physician or specialist for routine care or chronic condition management — they must travel back to their home service area or pay out-of-pocket.
PPO Medicare Advantage plans — typically allow out-of-network access to providers outside the service area with higher cost-sharing — but benefits vary significantly by plan. Some PPO plans provide reasonable out-of-area coverage while others provide minimal coverage.
The Snowbird Medicare Advantage Problem
For snowbirds spending 3 to 6 months in a different state Medicare Advantage plans create significant challenges:
- Chronic condition management — diabetes, heart disease, COPD — cannot be managed by a local Florida physician under most Medicare Advantage HMO plans
- Prescription refills — must often be obtained before the snowbird trip begins since formulary coverage may differ
- Physical therapy — typically requires in-network providers in the home state
- The snowbird must either return home for care or pay out of pocket for planned care in their winter state
This Medicare Advantage travel limitation is the most compelling reason why snowbirds and frequent travelers often choose Original Medicare with Medigap Plan G over Medicare Advantage — even if Medicare Advantage would otherwise be financially advantageous.
How Medigap Supplements Cover Travel Within the US
Medigap supplements — including Plan G and Plan N — provide supplemental coverage for Medicare-covered services at any Medicare-accepting provider in the United States. Since Medigap supplements follow Original Medicare’s nationwide provider access Medigap coverage is equally comprehensive in any US state.
Medigap Plan G and Travel
With Original Medicare and Medigap Plan G:
- Any Medicare-accepting provider in any state — covered at $0 after annual deductible
- No network restrictions — no prior authorization for routine care
- Snowbird-friendly — seamless coverage in both home and winter states
- Emergency care in any state — $0 after deductible
For snowbirds and frequent travelers Medigap Plan G is the gold standard — providing comprehensive coverage nationwide without any geographic restriction.
Does Medicare Cover International Travel?
Medicare and travel coverage outside the United States is one of the most frequently asked Medicare questions — and the answer for most Medicare beneficiaries is a firm no with very limited exceptions.
Original Medicare Does NOT Cover Care Outside the US
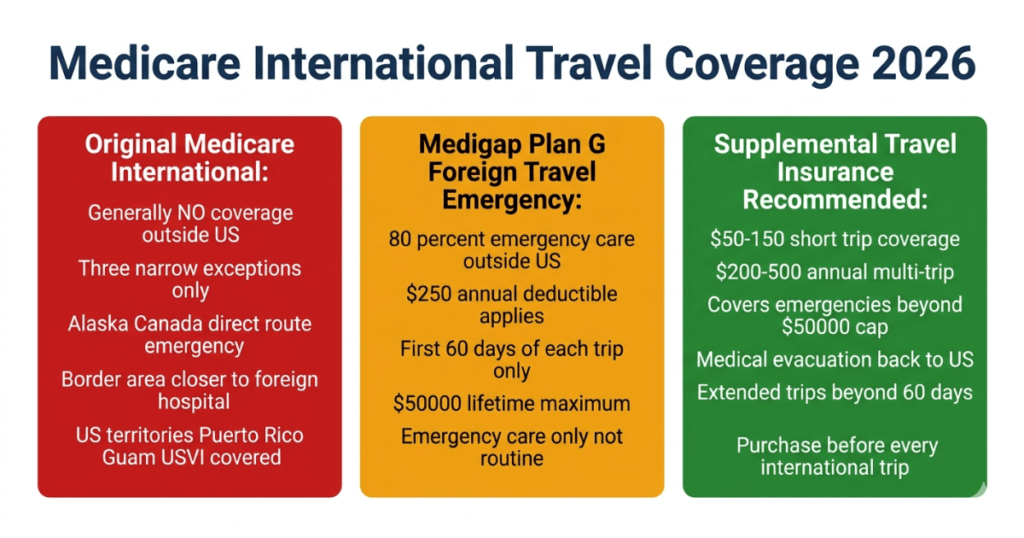
Original Medicare — Parts A and B — does not cover most medical care received outside the United States and its territories. If you travel to Europe, Canada, Mexico, Asia, or anywhere else outside the US and require medical care you will generally pay 100% out of pocket.
US Territories — Covered
Medicare does cover care in US territories:
- Puerto Rico — covered
- US Virgin Islands — covered
- Guam — covered
- American Samoa — covered
- Northern Mariana Islands — covered
Three Narrow Exceptions for International Coverage
Original Medicare has three very narrow exceptions where it may cover care in a foreign country:
Exception 1 — Canadian emergency for Alaskan residents: If you are traveling in Canada on a direct route between Alaska and the contiguous United States and a medical emergency arises Medicare may cover the care. This is a very specific geographic exception — not a general Canada travel benefit.
Exception 2 — Canadian emergency closer to Canadian hospital: If you are in the US near the Canadian border and the closest hospital is in Canada Medicare may cover emergency care at that Canadian hospital.
Exception 3 — Mexican emergency for border residents: Similar to the Canadian exception — if you are in a border area and a Mexican hospital is closer than any US hospital Medicare may cover emergency care.
These exceptions are extremely narrow — the vast majority of international medical expenses are not covered by Original Medicare.
Medigap Foreign Travel Emergency Benefit
Some Medigap plans provide a foreign travel emergency benefit — covering medical emergencies outside the United States during the first 60 days of a trip.
Medigap plans with foreign travel emergency benefit:
- Plan C — includes foreign travel emergency
- Plan D — includes foreign travel emergency
- Plan F — includes foreign travel emergency
- Plan G — includes foreign travel emergency
- Plan M — includes foreign travel emergency
- Plan N — includes foreign travel emergency
The Medigap foreign travel emergency benefit covers:
- 80% of the cost of emergency care outside the US — after a $250 annual deductible
- During the first 60 days of each trip
- For medically necessary emergency care
- Subject to a lifetime maximum of $50,000
This Medigap foreign travel benefit — while meaningful — is limited. It covers emergencies only — not routine care, and only for 60 days of each trip.
Medicare Advantage International Coverage
Medicare Advantage plans generally do not cover care outside the United States except in the same narrow circumstances as Original Medicare. Some premium Medicare Advantage plans offer additional international emergency coverage as an extra benefit — check your specific plan’s Evidence of Coverage document.
Medicare Travel Coverage for Snowbirds — Complete Guide
For the millions of American snowbirds who spend months away from home each year Medicare and travel coverage planning is essential.
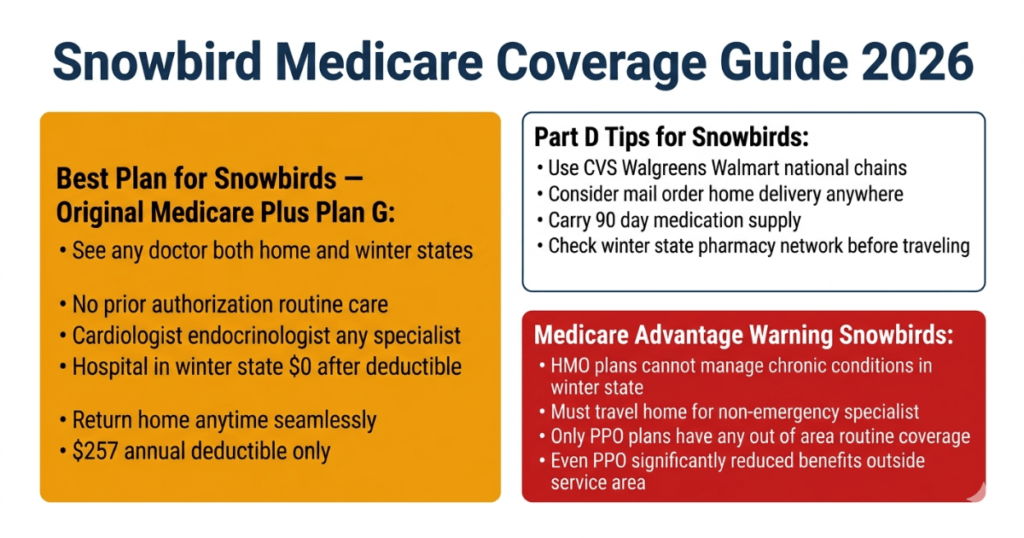
Best Medicare Option for Snowbirds — Original Medicare Plus Medigap Plan G
For snowbirds spending 3 to 6 months in a different state Original Medicare with Medigap Plan G is almost universally the recommended Medicare coverage:
- See any physician in your winter state at $0 after annual deductible
- No prior authorization for routine care
- Access specialists — cardiologist, endocrinologist, rheumatologist — in your winter home
- Hospitalization in your winter state at $0 after annual deductible
- Emergency care in any state at $0 after annual deductible
- Return home at any time and receive care seamlessly
Part D for Snowbirds
For Part D prescription drug coverage as a snowbird:
- Use national pharmacy chains — CVS Walgreens Walmart — in both states
- Consider mail order pharmacy — fills prescriptions shipped anywhere
- Check that your preferred winter state pharmacy is in your Part D plan’s network before traveling
- Carry a 90-day supply of chronic medications when traveling
Medicare Advantage for Snowbirds — Generally Not Recommended
For snowbirds spending more than 1 to 2 months away from home Medicare Advantage HMO plans are generally not appropriate — the network restrictions prevent routine care management in the winter state. Medicare Advantage PPO plans may provide more flexibility but benefits outside the service area are typically significantly reduced.
International Travel Insurance for Medicare Beneficiaries
Given that Original Medicare generally does not cover international care Medicare beneficiaries traveling abroad should strongly consider supplemental international travel medical insurance.
What International Travel Medical Insurance Covers
International travel medical insurance provides:
- Emergency medical care in foreign countries — hospitalizations, surgery, emergency physician care
- Medical evacuation — transport to appropriate medical facility including back to the US
- Dental emergencies — limited
- Trip interruption related to medical emergency
Travel Medical Insurance Costs
International travel medical insurance is typically very affordable:
- Short-trip (1 to 2 weeks) coverage — approximately $50 to $150 per person
- Annual multi-trip coverage — approximately $200 to $500 per person per year
- Medical evacuation coverage — approximately $50 to $200 additional per trip
Important for Medicare Beneficiaries Abroad
When traveling internationally carry:
- Medicare card — in case you return to the US for care
- Medigap card — for foreign travel emergency coverage
- Supplemental travel insurance policy information
- List of medications and doses
- Emergency contacts in the US
How to Prepare Your Medicare Coverage for Travel
Before major domestic or international travel Medicare beneficiaries should take these preparation steps:
Domestic Travel Preparation
- Confirm your Medicare card is current and not expired
- Carry your Medicare card and Medigap or Medicare Advantage card
- Know your Part D plan and carry a list of covered pharmacies at your destination
- Carry a 90-day supply of all chronic medications
- If Medicare Advantage — review your out-of-area coverage before traveling
- Know the location of hospitals and urgent care at your destination
International Travel Preparation
- Purchase supplemental international travel medical insurance
- Understand your Medigap foreign travel emergency benefit — 60-day limit $50,000 maximum
- Carry medication list and doctor contact information
- Know your plan’s foreign travel emergency procedures
- Carry copies of all insurance documents
Frequently Asked Questions — Medicare and Travel Coverage
Does Medicare cover me in other states?
Yes — Original Medicare covers medically necessary services at any Medicare-accepting provider in any US state. There are no geographic restrictions under Original Medicare. Medicare Advantage plans have network restrictions — emergency care is always covered but routine planned care outside your plan’s service area may not be.
Does Medicare cover snowbirds?
Original Medicare with Medigap Plan G is the best coverage for snowbirds — providing seamless coverage in both home and winter states at any Medicare provider. Medicare Advantage plans — particularly HMOs — are generally not appropriate for snowbirds because network restrictions prevent routine care management in the winter state.
Does Medicare cover medical care in Canada or Mexico?
Generally no — Original Medicare does not cover care in Canada or Mexico except in very limited specific circumstances — Alaskan residents in Canada, border emergencies at the nearest hospital. For travel to Canada or Mexico purchase supplemental international travel medical insurance.
Does Medigap Plan G cover international emergencies?
Yes — Medigap Plan G includes a foreign travel emergency benefit covering 80% of emergency care costs outside the US after a $250 annual deductible during the first 60 days of each trip up to a $50,000 lifetime maximum. This provides meaningful emergency protection but should be supplemented with additional travel insurance for extended or frequent international travel.
Should snowbirds choose Original Medicare or Medicare Advantage?
For snowbirds spending 3 to 6 months in a different state Original Medicare with Medigap Plan G is strongly recommended over Medicare Advantage. The nationwide coverage of Original Medicare with Plan G provides seamless care in both states — Medicare Advantage network restrictions typically prevent routine care management while snowbirding.
Summary — Medicare and Travel Coverage 2026
Medicare and travel coverage in 2026 presents dramatically different experiences depending on which type of Medicare coverage you have. Original Medicare provides seamless nationwide coverage at any Medicare-accepting provider — making it the best choice for travelers and snowbirds. Medicare Advantage plans provide strong emergency coverage but restrict planned non-emergency care to their service areas — a significant limitation for snowbirds and frequent travelers.
For international travel Original Medicare generally does not apply — the Medigap Plan G foreign travel emergency benefit provides meaningful emergency protection up to $50,000 but should be supplemented with dedicated international travel medical insurance for extended overseas travel.
For free help understanding your Medicare travel coverage options contact your State Health Insurance Assistance Program (SHIP) at shiphelp.org or call Medicare free at 1-800-633-4227.
This guide is for informational purposes only. Always verify current Medicare coverage details at Medicare.gov before traveling.
Sources: Medicare.gov | CMS.gov | SSA.gov | AARP.org
Last updated: April 2026 | Author: James Carter, Independent Medicare Research Analyst